Independent claim appraisal · All 46 counties
South Carolina Insurance Appraiser for claims that came up short
When the carrier accepts your claim but the check won’t cover the repair, South Carolina Insurance Appraiser prices the loss from scratch and takes it through the appraisal process written into your policy.
- Your appointed appraiser
- Line-item estimates by ZIP
- Homes, condos, HOAs & commercial
Why owners call
When the check doesn’t match the damage, call a South Carolina Insurance Appraiser
Most underpaid claims aren’t denied — they’re simply short. A slope left off the roof diagram, flooring that can’t be matched, a code upgrade nobody priced, a tree-removal line capped too low. South Carolina Insurance Appraiser exists for that space between “covered” and “paid in full.”
We don’t edit the carrier’s estimate. We inspect, measure and write our own, then compare the two line by line so you can see exactly where the money went missing.
How the firm works
✓Appraisal usually fits
- Coverage accepted, price disputed
- Repair-or-replace and matching arguments
- Missing trades, code items or overhead and profit
- Roof measurements and steep or high charges
✕Usually not the right tool
- A full denial of coverage
- Bad-faith or other legal claims
- A gap too small to justify the fees
- A deadline that needs an attorney first
Services
What a South Carolina Insurance Appraiser handles
Twelve services built around one job: a valuation of your loss that stands up to the other side. Start with an estimate review, or bring us in once appraisal has been demanded.
 01
Appraisal Demand Representation
We act as the appraiser you name after a South Carolina appraisal demand is made by you or your insurer.
Learn more 02
Home Insurance Appraisal
Independent appraisal for homeowners whose insurer accepted the claim but paid far less than repairs cost.
Learn more 03
Commercial & HOA Appraisal
Appraisal for HOAs, condo associations, churches, retail centers and apartment owners with disputed property claims.
Learn more 04
Roof & Hail Damage Appraisal
Appraisal for roof claims where slopes, matching, code items or hail bruising are in dispute.
Learn more 05
Wind & Tornado Claim Appraisal
Appraisal for straight-line wind and tornado claims, from torn shingles to structural damage.
Learn more 06
Hurricane Claim Appraisal
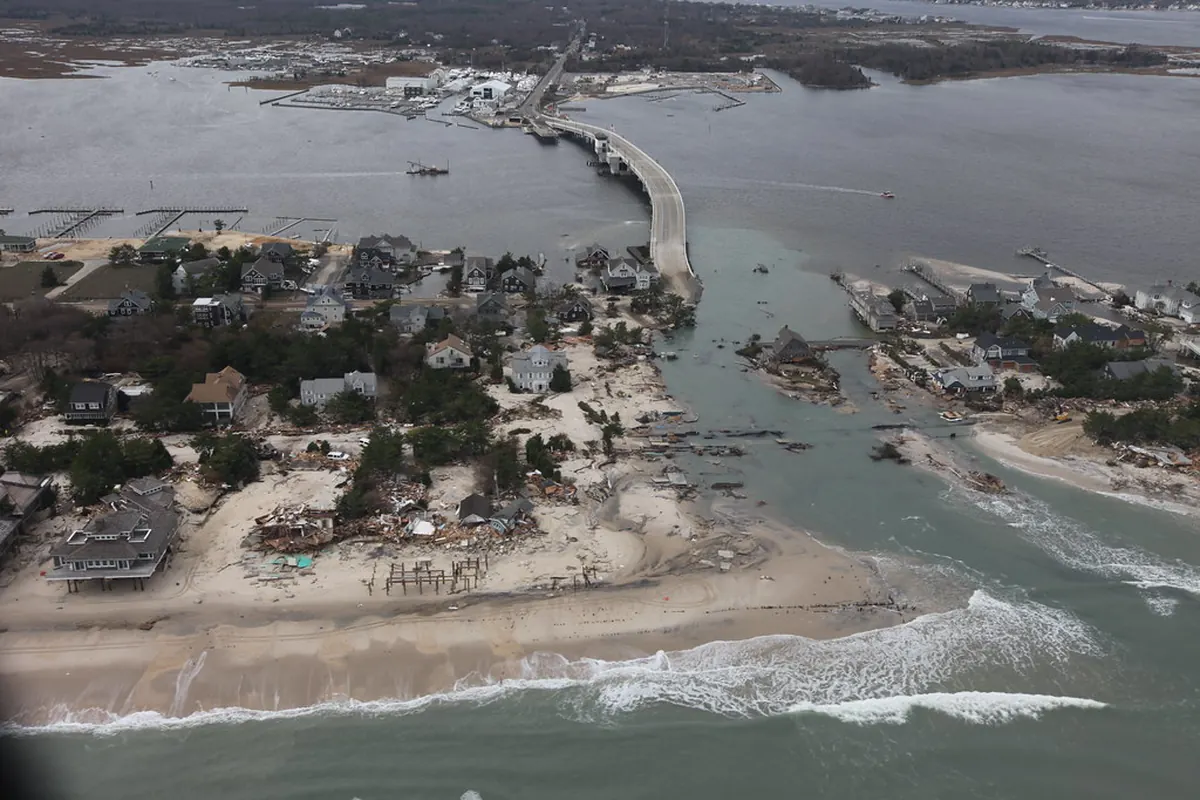
Appraisal for hurricane and tropical storm claims, including SCWHUA wind policies and split wind/flood losses.
Learn more 07
Water Damage Claim Appraisal
Appraisal for burst pipes, appliance leaks, roof leaks and other sudden water losses that were underpaid.
Learn more 08
Fire & Smoke Damage Appraisal
Appraisal for fire, smoke, soot and lightning losses where cleaning, rebuild or contents values are disputed.
Learn more 09
Tree Fall & Ice Storm Appraisal
Appraisal for homes damaged by falling trees and limbs after hurricanes, thunderstorms or ice storms.
Learn moreFive claim climates
One state, five ways storms show up on a roof
A South Carolina Insurance Appraiser has to read the damage differently in a Beaufort single house, a Greenville split-level and a Myrtle Beach condo tower. Here’s what we see most in each region.
Lowcountry
Hugo, Matthew, Irma and Ian all left their mark here. Elevated homes, single houses with piazzas and wind-pool policies make for layered claims.
Upstate
Helene in 2024 showed how far inland a hurricane can reach. Spring hail and winter ice keep roofers busy across the foothills.
Midlands
The 2015 flood and the 2014 ice storm are still the reference points for water and tree claims around the capital and Aiken County.
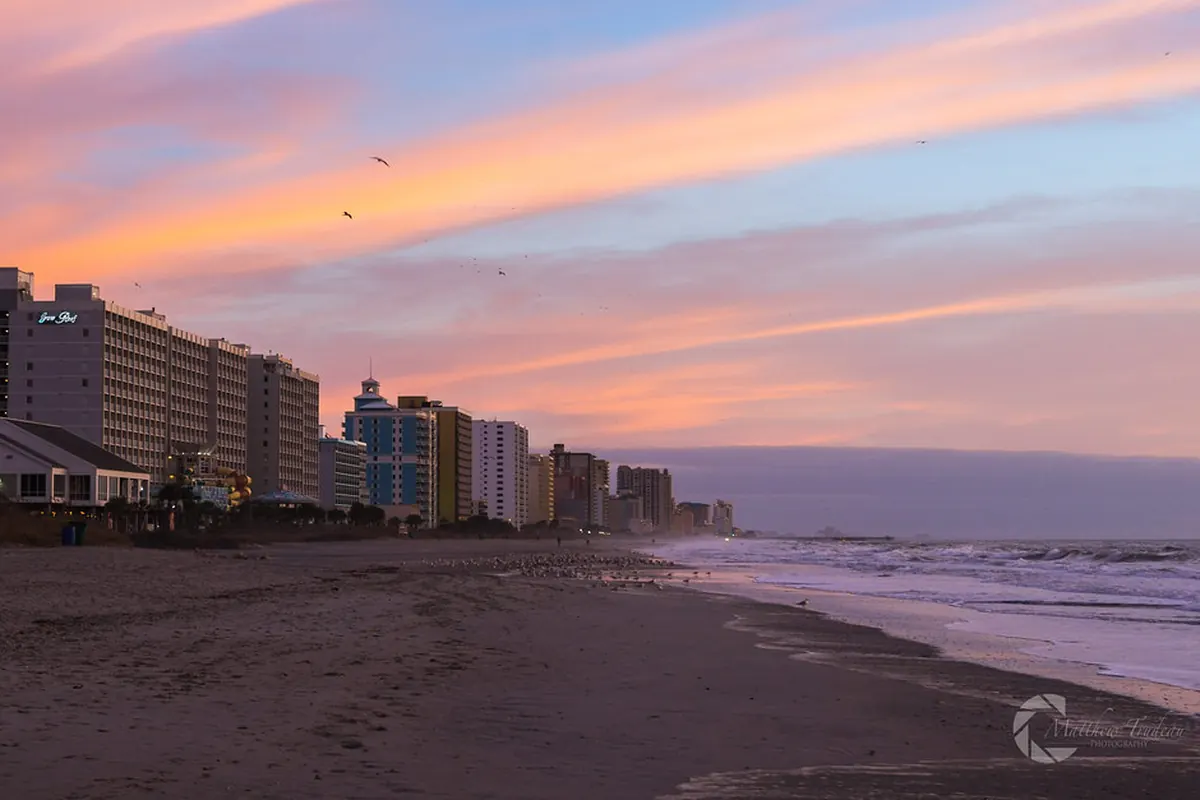
Grand Strand
High-rise condos, vacation rentals and Florence-era river flooding put master policies and flood coverage at the center of disputes.
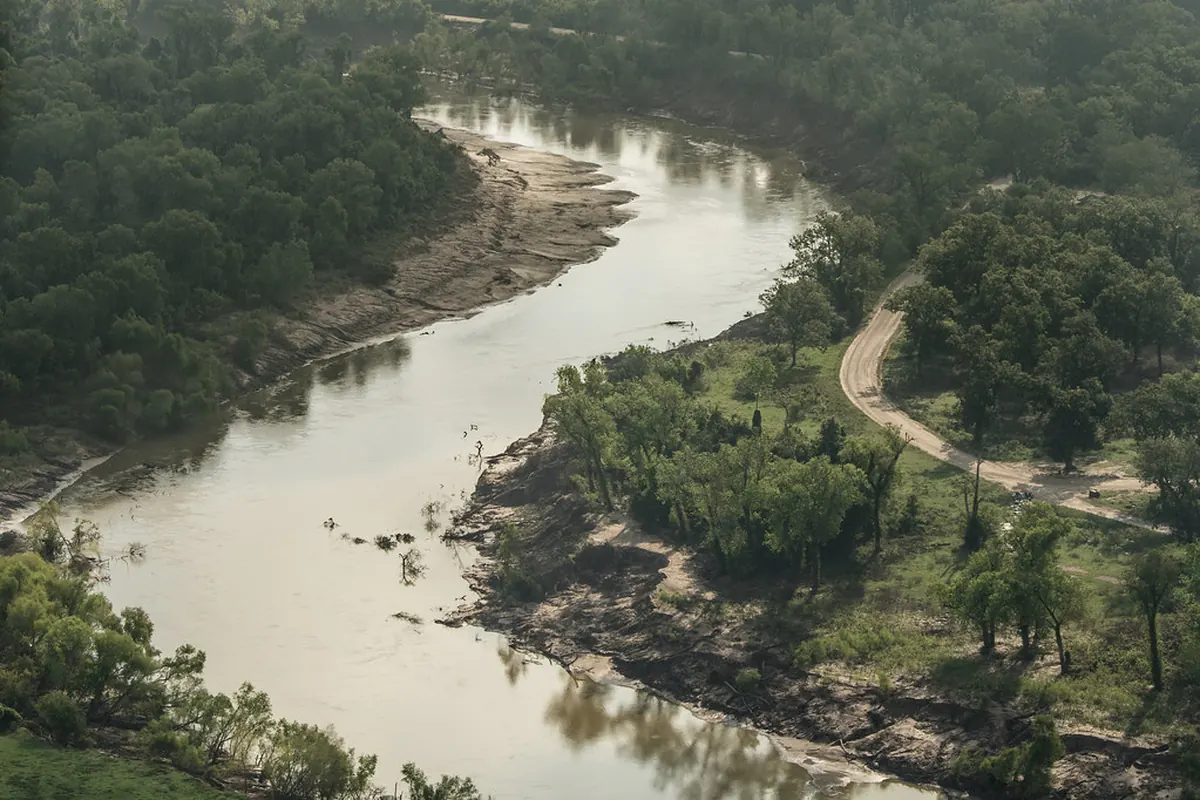
Pee Dee
Rivers rise for days after a coastal storm. Homes, farm outbuildings and small commercial buildings often share one claim.
The process
How appraisal moves a stuck claim
The appraisal clause turns an open-ended argument into a defined process with a binding result. This is how South Carolina Insurance Appraiser takes a file from the first call to a signed award.
Free review
We read the policy, the carrier’s estimate and your photos, then tell you whether appraisal fits.
Our own scope
We inspect, measure and build a line-item estimate priced for your South Carolina ZIP code.
Written demand
Appraisal is demanded in writing and we are named as your appraiser on time.
Appraiser talks
We work through the differences with the carrier’s appraiser, line by line.
Umpire if needed
Items still open go to a neutral umpire with photos and pricing support.
Signed award
Two of three signatures set the amount of loss and payment follows the policy.
Free & private
Free claim tools from South Carolina Insurance Appraiser
Check the math before you pick up the phone. Every tool runs in your browser, and nothing you type is stored or sent.
Illustrative figures. The full claim gap & fee estimator adds appraiser and umpire fees so you can see a net number.
RCV vs. ACV Holdback Calculator
List damaged items by age and life to estimate your first check, the holdback and the final total.
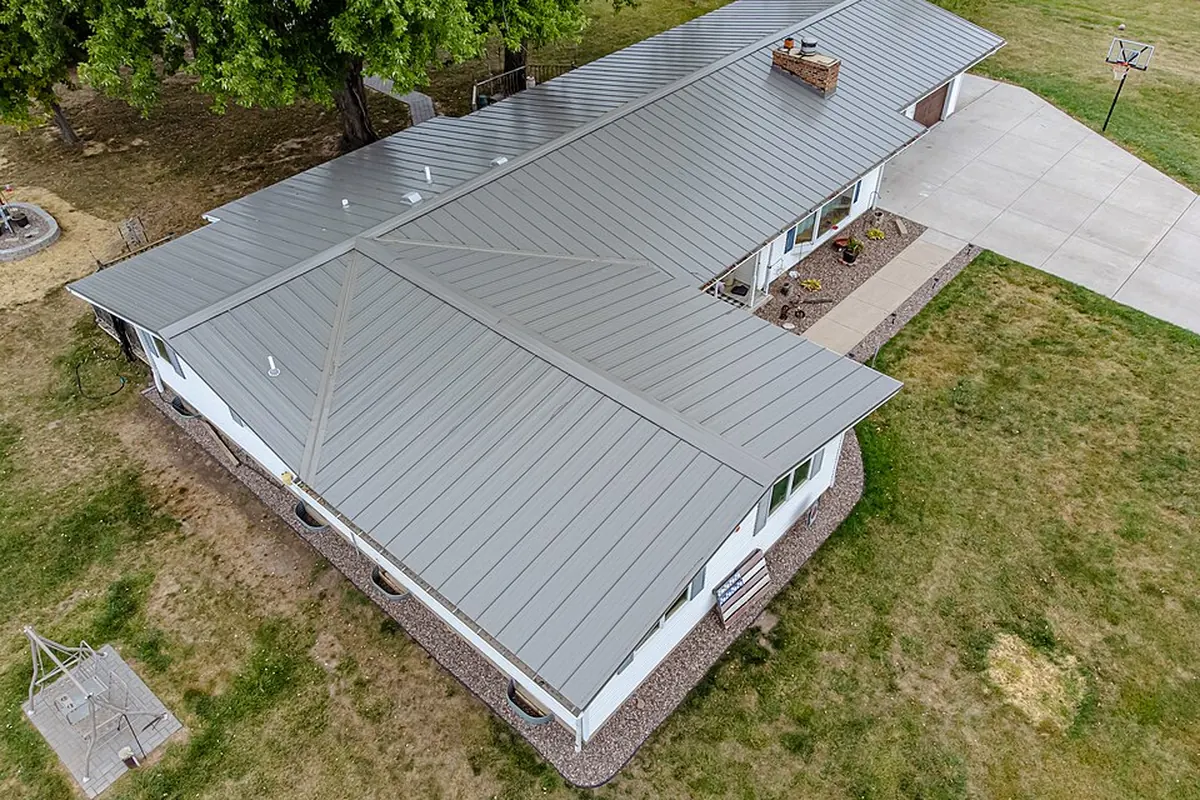
Roof Area & Pitch Estimator
Turn a footprint and pitch into sloped area, squares, bundles and a steep-charge check.
Hurricane Deductible Calculator
Convert a percentage hurricane or named-storm deductible into dollars and see what a claim pays.
Claim Timeline Builder
Map notice, proof of loss, holdback and suit dates from your date of loss, then export to a calendar.
Appraisal Readiness Checkup
Twelve yes/no questions that score your claim file and build a to-do list before you demand appraisal.
Wind vs. Flood Damage Splitter
Split a hurricane loss between a wind policy and a flood policy to see who pays what — and what’s left.
Storm history
The storms that shaped South Carolina claims
Every adjuster and every South Carolina Insurance Appraiser in the state measures new losses against these events. Scroll the timeline.
Hurricane Hazel
Struck the Grand Strand in October, reshaping beachfront building along Horry County.
Hurricane Hugo
Category 4 landfall near Charleston, with damage reaching Sumter and the Midlands.
The October flood
Record rain overwhelmed creeks and dams around Columbia and the Midlands.
Hurricane Matthew
Landfall near McClellanville; huge tree losses on Hilton Head and in Beaufort County.
Hurricane Florence
Record river flooding in the Pee Dee and Horry County for weeks after landfall.
Hurricane Ian
Landfall near Georgetown, with wind and surge along the coast.
Hurricane Helene
Destructive wind and tree fall across the Upstate and Aiken County, far from the coast.
Locations
South Carolina Insurance Appraiser locations across the state
We travel to every county. These are the communities where South Carolina Insurance Appraiser handles claims most often, each with its own page of local detail.
Charleston
Charleston & Berkeley Counties
Local claimsColumbia
Richland & Lexington Counties
Local claimsGreenville
Greenville County
Local claimsMyrtle Beach
Horry County
Local claimsSpartanburg
Spartanburg County
Local claims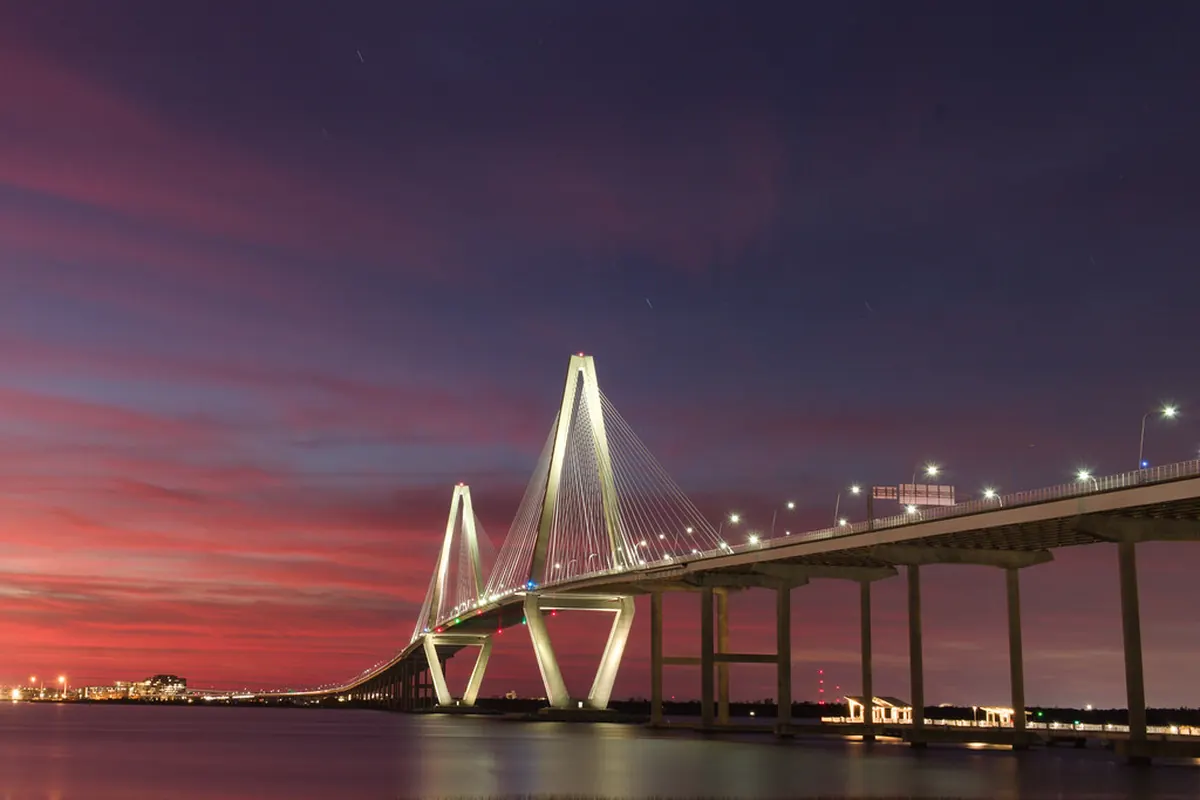
Mount Pleasant
Charleston County
Local claims
Summerville
Dorchester, Berkeley & Charleston Counties
Local claims
Rock Hill
York County
Local claimsChoosing help
Appraiser, public adjuster or attorney?
Each solves a different problem. South Carolina Insurance Appraiser will tell you when someone else is the better call.
South Carolina Insurance Appraiser
- Main job
- Values the amount of loss
- Best moment
- Coverage accepted, number disputed
- Outcome
- Award signed by two of three
Public adjuster
- Main job
- Prepares and negotiates the claim
- Best moment
- Early, soon after the loss
- Outcome
- Negotiated settlement
Attorney
- Main job
- Legal rights, coverage and bad faith
- Best moment
- Denials and close deadlines
- Outcome
- Settlement or judgment
FAQ
Questions people ask a South Carolina Insurance Appraiser
Short, straight answers. The full FAQ covers costs, timing and South Carolina specifics.
What does a South Carolina Insurance Appraiser do?
A South Carolina Insurance Appraiser values the damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, when needed, present open items to a neutral umpire.
How is an appraiser different from a public adjuster?
A public adjuster handles and negotiates the whole claim. An appraiser works within the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
Can appraisal settle a wind-versus-flood argument?
It can value the wind damage under the wind policy, but whether an item was caused by wind or water may be treated as a coverage question. Flood policies have their own rules. Good photos and water-line evidence matter most.
Is the award binding?
On the amount of loss, generally yes, once any two of the three panel members sign. Coverage questions and legal claims sit outside appraisal.
What does it cost?
Each side pays its own appraiser and usually half of the umpire. We put our fee in writing before any work begins, and the first conversation is free.
Where does a South Carolina Insurance Appraiser work?
Statewide — all 46 counties, with regular work in Charleston, Columbia, Greenville, Myrtle Beach, Hilton Head Island, Beaufort, Florence, Rock Hill and Aiken.
Guides
Read this before you demand appraisal
Practical guides from South Carolina Insurance Appraiser on hurricane deductibles, tree claims, wind-pool policies and documentation.
Hurricane Deductible in South Carolina: Triggers, Math and Disputes
Percentage deductibles can swallow a coastal claim. Here’s how triggers work, how the math runs and where disputes really start.
Read the guideWhen a Tree Falls on Your House: A Tree Fall Insurance Claim Guide
Helene dropped trees on thousands of Upstate and Aiken County homes. What policies usually pay for, what gets missed and when appraisal helps.
Read the guide
Wind Pool Claims and Appraisal: SCWHUA, Homeowners and Flood
Many coastal homes carry three policies for one storm. How SCWHUA, homeowners and flood claims interact, and where appraisal helps.
Read the guideFree first review
The best time to check the numbers is before you accept them
A short review now can keep you from signing off on a settlement that won’t pay for the repair.
Start with a conversation
Talk to a South Carolina Insurance Appraiser about your claim
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal makes sense — no pressure and no obligation.
- Call or text+1 (844) 537-1427
- HoursMon–Fri, 8am–6pm ET
- CoverageAll 46 South Carolina counties